AI agent for loan officers
Pre-Approval Expiry and Renewal Agent
No buyer is left with an expired or inaccurate pre-approval, and each renewal reflects current facts
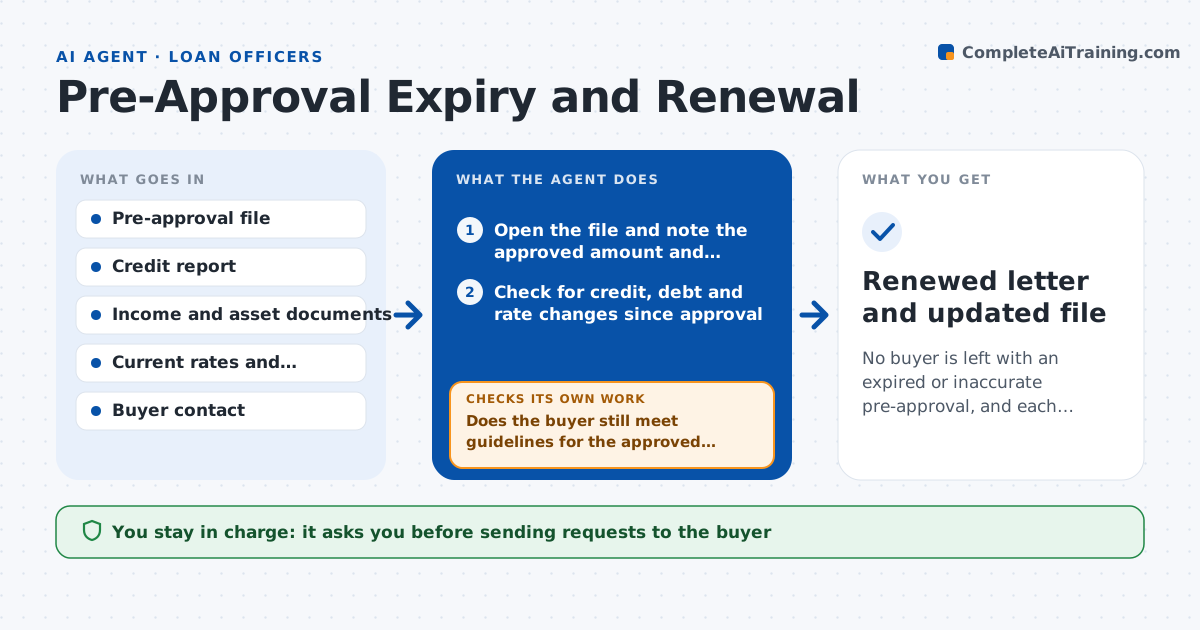
What it does
A pre-approval letter lasts 60 to 90 days, and many buyers are still looking when it ends. Credit, income or rates may have changed, so the old letter is no longer safe to rely on. This agent tracks the expiry date of every letter. About 14 days before, it checks for changes: new credit pulls, new debts, job changes in the file and rate moves. It writes to the buyer with a request for updated pay stubs and bank statements. Once documents arrive, it rechecks eligibility against current guidelines, rebuilds the numbers and drafts a renewed letter or a revised amount. If the buyer no longer qualifies for the old amount, it explains the difference. The loan officer approves every renewed letter and all contact. Edge case: the buyer opened a car loan, and the debt ratio now fails.
How it works
Follow the arrows from top to bottom. The orange dashed arrow is the loop: when a check fails, the agent goes back and tries again.
Read the steps as a list
- A pre-approval is 14 days from expiry
- Open the file and note the approved amount and conditions
- Check for credit, debt and rate changes since approval
- Draft a request to the buyer for updated documents
- Loan officer approves the request messageThe agent waits here for your OK.
- Review the new documents when they arrive
- Recalculate income, debts, assets and ratios at today's rate
- Does the buyer still meet guidelines for the approved amount?If not: calculate the new qualifying amount and prepare an explanation. Back to step 7.
- Were all required documents received?If not: send a reminder every three days until the date of expiry and mark the file at risk. Back to step 6.
- Loan officer approves the renewed or revised letterThe agent waits here for your OK.
- Renewed letter and updated file
How it decides
It renews only when updated documents show debt-to-income, credit and assets still meet the guidelines at the current rate, and it revises the amount when they do not.
- Start the renewal at 14 days before expiry
- Require pay stubs from the last 30 days
- Revise the amount if debt-to-income exceeds 45%
- Mark files at risk if documents are missing 5 days before expiry
Make it yours
Every agent is a starting point. You choose these settings for your own situation.
- Days before expiry to start (default 14)
- Maximum debt ratio (default 45%)
- Documents required
- Reminder frequency (default every 3 days)
What keeps you in control
It always asks you first
- Sending requests to the buyer
- Issuing a renewed or revised letter
Hard limits
- Never issues a letter without loan officer approval
- Never pulls credit without consent
- Does not promise a rate
It stops when
- Done: letter is renewed, revised or allowed to lapse by the buyer
- Stop: the buyer cannot be reached or consent for credit pull is missing
Set it up
We guide you through the set-up, step by step
Members get the full set-up guide for this agent. No technical skills needed: you copy, paste and upload.
- One set of instructions to paste into your AI, with the clicks for ChatGPT, Claude, Microsoft 365 Copilot, Gemini and Grok
- The agent then walks you through connecting your own data, one source at a time
- A downloadable copy with the flow chart, the rules and the full guide